IndiaCarbonMoves | CCTS20205 From Chalkboards to Carbon Boards
Kicking off the Carbon_Credit_ComplianceChapter
Markets mature not when they grow, but when they’re held accountable. India just made carbon compliance bankable.
KtalystKeystone
India just dropped a carbon bombshell (the good kind!)
The April2025 Gazette brings GHG Emission Intensity (GEI) targets under the Carbon Credit Trading Scheme (CCTS), 2023—and it’s not optional anymore.
What’sHappening?
A market with a mission. A mandate with math.
BaselineToTarget: 140+ industrial giants get official GEI targets from 2023–24 levels to 2026–27
PenaltyProof: Miss your target? Pay up—2x the average carbon credit price
ComplianceStartsNow: Welcome to India’s first enforceable carbon intensity regime
FunData (but serious):
Vedanta Jharsuguda (Aluminium): Drop from 13.49 → 12.83 tCO₂e/ton
UltraTech Bela (MP): From 0.8351 → 0.8093 tCO₂e/ton
JK White Cement, Gotan: From 0.8743 → 0.8461 tCO₂e/ton
CarbonMoves You Can’t Ignore:
(aka the not-so-fine print)
LegalArmour: Penalties enforced under the Environment Protection Act, 1986
DigitalByDesign: Full compliance and credit tracking via the Indian Carbon Market Portal
CreditMath: Emission gap × output = carbon credits owed or earned
BankItToWinIt: Overachievers? Store surplus credits for future cycles
NoEscapeClause: Grinding units, refineries, even white cement—no one’s exempt
HotspotLogic: Aluminium + Cement = 25%+ of India’s industrial emissions
PenaltyPath: Fail on compliance? CPCB fines = 2x avg. credit price
PublicScrutiny: 60-day window open to file suggestions or objections to MoEFCC
WhatTheLeadersSay
This is India’s carbon market growing a spine. Industry must now move from pledges to performance.
R. K. Singh, Union Minister for Power & New & Renewable Energy
Emission targets will push Indian industries to global competitiveness while greening their core.
Ajay Mathur, DG, International Solar Alliance
CCTS 2025 is not just compliance—it’s carbon accountability.
Sumant Sinha, CEO, ReNew Power
KtalystTake
India’s carbon market just flipped the script—from voluntary virtue-signaling to regulated results.
This is no longer ESG fluff—this is hard math.
You can’t manage what you don’t measure. Now, you can’t skip what you didn’t meet.
Ready to benchmark your GEI or decode this carbon chessboard? Let’s connect.
CCTS IndiaCarbonMarket GHGTargets ComplianceEra NetZeroIndia SustainabilityStrategy KtalystKeystone ESGCompliance ClimateActionIndia
Source / shared link: https://carbon-pulse.com/389823/?utm_source=chatgpt.com
Originally published on LinkedIn on 2025-04-22 05:48:00: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A4385073-7320322463400181760
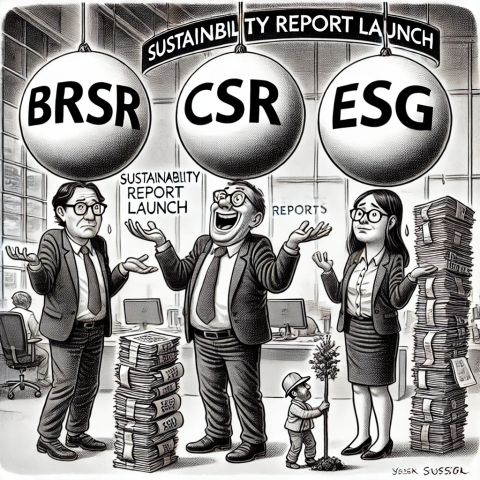
🚨 BRSR, CSR & ESG: Invading the Thin Line Between Sustainability & Showbiz! 🎭💰♻️
📌 RealityCheck:
CSR = Spending money.
BRSR = Reporting about spending money.
ESG = Rating the reports on spending money. None ensure real impact!
If a company plants a tree but spends twice as much marketing it—did it really go green?
In India’s corporate boardrooms, BRSR (Business Responsibility and Sustainability Reporting), CSR (Corporate Social Responsibility), and ESG (Environmental, Social, and Governance) are now mandatory checkboxes—but are they driving real impact or just polished PR campaigns?
🧐 BRSR vs. CSR vs. ESG: What’s Actually Happening?
🔹 CSR (Spend to Pretend?)
✔️ Companies must spend 2% of net profits on “good causes.” (Companies Act, 2013)
✔️ #₹14,300 Cr ($1.7B) spent in 2024—but 47% went to company-affiliated NGOs. (MCA, 2025)
✔️ Only 27% of CSR funds linked to sustainability. (SEBI, 2025)
🔹 BRSR (Report to Impress?)
✔️ Mandatory ESG disclosures for the top 1,000 listed firms. (SEBI, 2022)
✔️ 62% of reports claim “sustainability progress”—but no third-party verification. (ESG India, 2025)
✔️ 88% of firms skip reporting Scope 3 emissions (indirect pollution). (SEBI, 2025)
🔹 ESG (Ratings to Manipulate?)
✔️ Over $35T in global assets claim ‘ESG compliance’—but 70% lack real sustainability actions. (Morningstar, 2025)
✔️ India ranked 120th in ESG adoption—lagging behind Vietnam & Indonesia. (WEF, 2025)
✔️ 52% of ESG funds globally are now under scrutiny for ‘greenwashing’ claims. (EU Green Finance Report, 2025)
💰 Follow the Money: Greenwashing in Disguise?
🚨 If CSR was a school project, most companies would fail for copying answers.
🚨 If BRSR was a medical check-up, it would be self-diagnosed with no lab tests.
🚨 If ESG was a cricket match, most firms would just focus on looking good in the highlights.
🔎 Who’s Actually Doing Something?
🏆 The Real Deal:
✅ Tata Group: Large-scale renewable projects & real net-zero efforts.
✅ ITC: Circular economy & carbon-positive initiatives beyond paper.
✅ Hindustan Unilever: Science-based net-zero targets & sustainable sourcing.
🚨 The Greenwashers:
❌ Reliance: Talking renewables but expanding fossil fuel projects.
❌ Adani: Carbon-neutral claims exposed as accounting tricks.
❌ Vedanta: Reports “social impact,” but fined ₹120 Cr for pollution violations in 2024.

Originally published on LinkedIn on 2025-02-19 14:07:18: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7297980065252843524
YR2024_India’s Bioenergy Capacity Hits New Milestone
India has reached a significant milestone in its clean energy efforts, with bioenergy playing a key role in the renewable energy mix. As of 13th November_2024, bioenergy contributes significantly to India’s renewable portfolio, supporting the country’s transition toward net-zero emissions by 2070.
With advancements in biogas, bioethanol, bio_CNG, and biomass power, India is accelerating its clean energy goals:
Bioenergy (~6%) now forms a critical part of the 46.3% renewable energy share in the total installed power capacity.
The sector supports decarbonization in transportation, industry, and aviation through initiatives like bioethanol blending and Sustainable Aviation Fuel (SAF).
India’s bioenergy growth reflects its focus on reducing fossil fuel dependency while strengthening its $20 billion bioeconomy, creating a sustainable and greener energy future.
India’s Bioenergy Partnerships in 2024
✅ TruAlt Bioenergy & Sumitomo Corporation
Focus: Biogas, Bioethanol, SAF
Target: Cutting fossil fuel dependency by 50%.
✅ ISMA, TERI & Praj Industries
Focus: SAF, Green Hydrogen
Target: 12 billion liters SAF annually by 2030.
✅ India_Brazil SAF Collaboration
Focus: SAF Supply Chain Optimization
✅ BPCL ($170M Investment)
Focus: SAF Production
Target: 5% SAF blending by 2030.
✅ IOC & LanzaJet
Focus: Waste-to-Ethanol SAF
Output: 80,000 metric tons annually.
✅ GPS Renewables & SAF One
Focus: Aviation Emission Reduction (8% GHG emissions).
✅ Adani Total Gas & Greenko Group
Focus: Biogas, Green Hydrogen
Impact: 10% reduction in industrial emissions by 2035.
✅ Reliance & Air Products
Focus: Bioethanol, SAF
Strengthening the $20 billion bioeconomy.
✅ Tata Power & Shell India
Focus: Bio-CNG, Biogas
Target: 5M metric tons annually by 2030.
✅ NTPC & Honeywell International
Focus: Green Methanol, SAF
Emissions Reduction: 20% by 2035.
✅ Vedanta & EcoEnergy Europe
Focus: Waste-to-Bioethanol
Target: 20% ethanol blending by 2025.
✅ L&T & Siemens Energy
Focus: Biohydrogen
Target: 1M metric tons annually by 2030.
Why This Matters
India’s bioenergy partnerships are driving innovation, emissions reduction, and economic growth.
📊 Key Stats:
50% fossil fuel dependency reduction by 2030.
12B liters SAF production annually by 2030.
20% ethanol blending by 2025.
5M metric tons of biogas production annually.
1M metric tons of biohydrogen by 2030.
India is laying the foundation for a sustainable and net-zero tomorrow, proving that collaboration is key to progress.
Source / shared link: https://pib.gov.in/PressReleaseIframePage.aspx?PRID=2073038
Originally published on LinkedIn on 2024-12-17 15:02:29: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A3880479-7274801133875822593

