Protectionism is temporary. Strategy is forever.” – KtalystKeystone
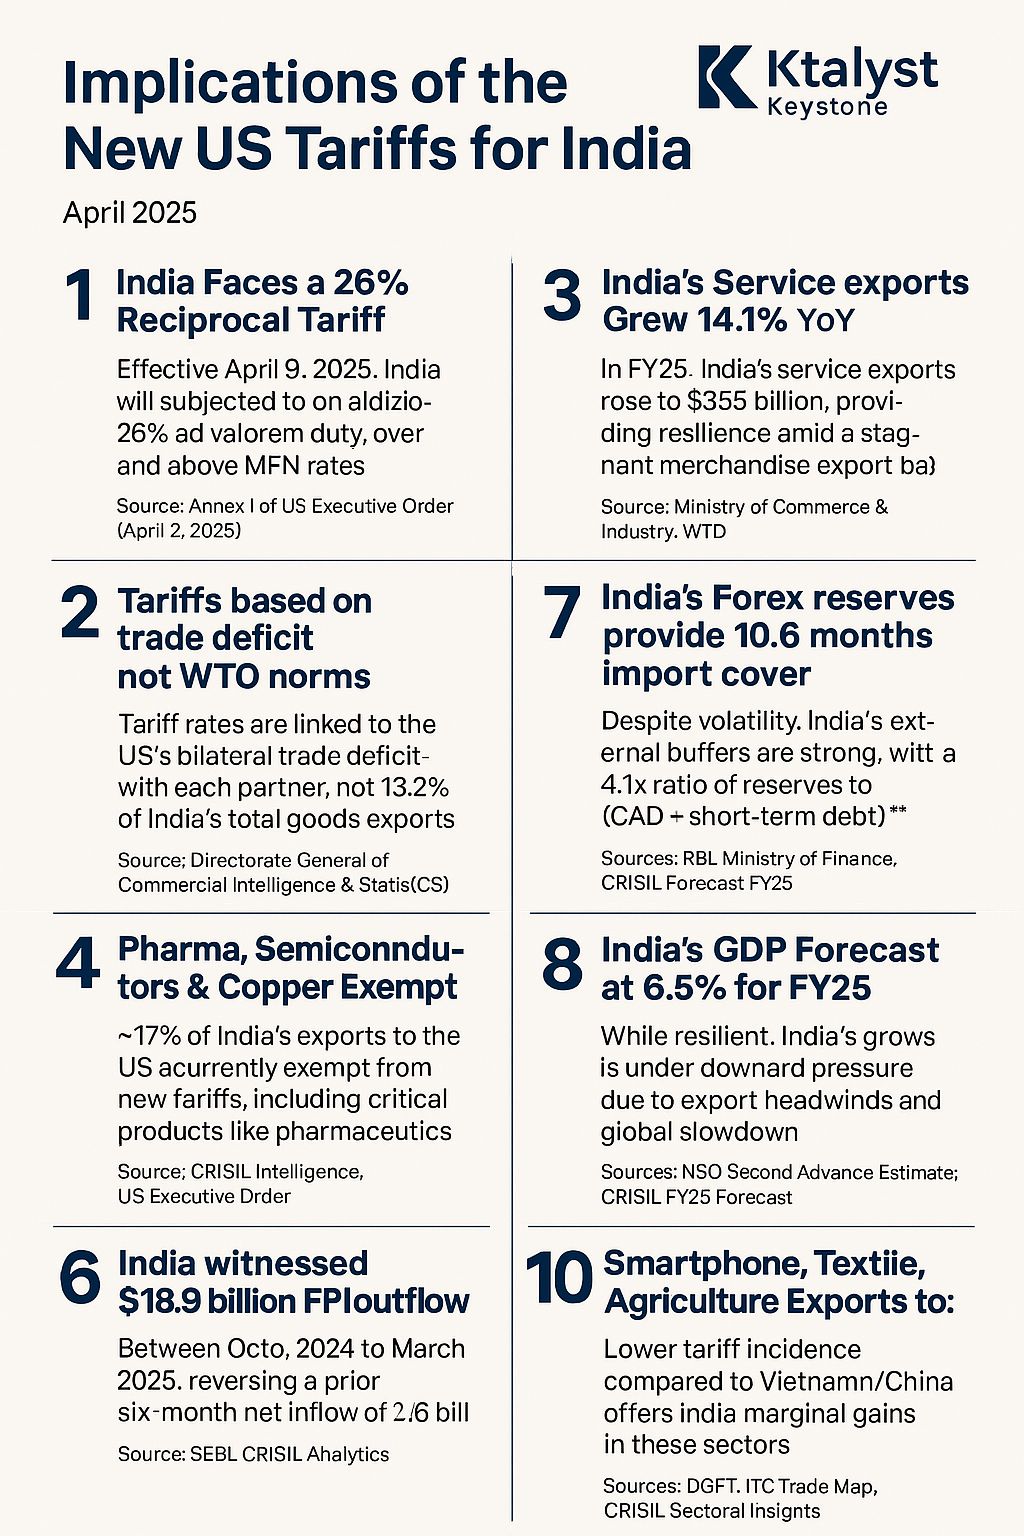
Insights from the April 2025 CRISIL Report on US Tariffs & India:
The 26% tariff isn’t just a tax — it’s a test. A test of India Inc.’s resilience, agility, and strategic depth.
India’s export engines may sputter, but its services superpower and domestic strength are the new fuel.
StrategicViewpoint | What IndianBusinesses Must Do Now
🔍 RethinkExportDependency
High-risk sectors like GemsAndJewellery (with 37% exports to US) must unlock new geographies — EU, GCC, ASEAN.
📦 LeverageServicesBoom
With service exports clocking 14.1%YoY growth, the pivot to digital, consulting, and R&D is more than necessary — it’s non-negotiable.
⚙️ LocalizeValueChains
Auto and Electronics firms must evaluate USMCA partnerships and nearshoring to maintain tariff competitiveness.
📈 HedgeWisely
$18.9B of FPI outflows signal clear volatility. CFOs, it’s time to sharpen your forex strategy and revisit pricing models.
🛡️ UseIndiaPolicyCushion
The PLI schemes, ongoing capex push, and FTA progress (esp. with UK & EU) can soften the blow.
🌱 StayResilientStayStrategic
India’s #$355B service exports, 10.6 months import cover, and low CAD are not just stats — they’re shock absorbers.
KtalystKeystone | CatalysingStrategy in Disruptive Times
TradePolicy GlobalMarkets IndiaUS TariffWatch Exports Geopolitics MakeInIndia KtalystPerspective LinkedInPulse

Originally published on LinkedIn on 2025-04-08 17:38:16: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A2153908-7315427778760183808
AprilFool came a little late this year? 2ndApril, 2025 – Liberation Day or Global Meltdown?
Markets Crash: Trumpets Roars Back
When giants sneeze, the world catches tariffs.” – Anju Sharma Sharma
Global Market Fallout – Snapshot
Wall Street
S&P 500: -2.5%
Dow Jones: -700 pts (-2.1%)
Nasdaq: -3.0%
Biggest one-day drop since 2023.
Tech & auto stocks hit hardest.
Europe
DAX (Germany): -2.8%
CAC 40 (France): -2.5%
FTSE 100 (UK): -2.3%
Fear of retaliatory EU tariffs.
Asia
Nikkei (Japan): -2.9%
KOSPI (Korea): -3.1%
Shanghai Composite: -2.7%
Export economies brace for impact.
Commodities & Currencies
Gold: +3% ($1950/oz) – Safe haven rush
Oil: -2.5% ($58/barrel) – Demand fears
USD Index: +1.4% – Dollar dominates
Euro & Yen: Slide sharply against USD
Sector Impacts
Autos: Ford -4%, GM -3.8%, Hyundai -5%
Tech: Apple -3.5%, Microsoft -3.2%, Samsung -4.4%
Pharma: Cipla -3.1%, Teva -2.6% (India & Israel-based suppliers hit)
AnalystForecasts
Goldman Sachs: Cuts U.S. GDP forecast by 0.5%
Morgan Stanley: Predicts 1.4% drop in global GDP if escalation continues
Bloomberg: Warns of a “1990s-style dislocation in global trade flows
InvestorMood
Flight to safety: Treasuries & gold up
High volatility: VIX Index +21%
Risk-off sentiment dominates
Brace, don’t chase,” advises BlackRock.


Originally published on LinkedIn on 2025-04-02 13:39:28: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7313193352487755791

