TheGreatLubricantExit
Legacy, Liquidated:
EnergyGiants PivotProfitPrune
What’s Happening?
Energy titans are unloading slow-yield gems to double down on high-return assets.
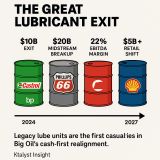
BP → Castrol (Lubricants):
Divestment Value: $8–10B
Castrol India Stake: ₹11,000 Cr ($1.26B)
Trigger: Elliott’s 5% stake + demand for 40% higher FCF by 2027
Action: Cutting low-carbon spend by $4B; boosting oil/gas CAPEX to $10B/year
Phillips66:
Activist Pressure: Elliott again
Ask: Separate midstream; boost refining-led returns
Potential Asset Trim: $15–20B in pipelines and logistics
Shell:
Retail Exit: 1,000+ sites by 2025
Focus Shift: EV charging, premium fluids, convenience tech
Implication: $3–5B retail realignment underway
KtalystInsight: Reading Between the (Oil) Lines
Lubricants are profit-rich but future-weak (avg. EBITDA margin ~22%)
Yet low growth (~2% CAGR globally) makes them divestable in energy transition math
Investors want “fast returns, not long transitions
Fossil CAPEX now delivers 3–4x faster IRR vs green infra over 5 years
We’re witnessing a $50–70B asset reshuffle till 2027
Legacy BUs like lubricants, midstream, retail will change hands
Expect strategic buyers: Aramco (Castrol), PE firms (Shell retail), Indian majors (Castrol India)
Energy companies are becoming capital allocators, not asset hoarders
ROACE > ESG scorecards in current boardroom calculus
TheNext battleground? Mid-tier suppliers and private equity deals in Asia, MENA, LATAM
Buying old gold to quietly mint green profits
Sometimes, it’s not a shift. It’s a shuffle with sharper cards.” – KtalystKeystone


Originally published on LinkedIn on 2025-04-25 18:23:18: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7321599702188060673

