EU_90% ClimateMandate: Europe Didn’t Pass a Law, It Pulled the Future Forward
Europe just changed the rules of the global economy.
A 90% cut in greenhouse gases by YR2040 is not a climate target
it is a continental reboot, a rewiring of how energy, industry, capital, and competitiveness will function for the next generation.
Europe must shrink_its_emissions from 4.3 billion tonnes → below 430 million tonnes. That is not a policy shift. That is a planetary pivot.
What This Really Means (Forget the Headlines)
Europe has installed a carbonbrain
This mandate forces every industry to re-learn how to breathe
power, steel, cement, chemicals, transport, buildings. Everything must now move on clean electrons, green molecules, or captured carbon.
This is an economic rewiring, not an environmental one.
CarbonRemovals become the new industrial organs
1) Direct air capture.
2) Bioenergy with carbon storage.
3) Mineralisation.
4) Nature-based sinks.
All once experimental.
Now mandatory anatomy of the European economy.
NamasteIndia, LATAM & Africa become the world’s climate orchards
Europe will need hundreds of millions of tonnes of high-integrity climate contributions.
India alone can offer 30–40 million tonnes from bioenergy, agro-waste, regenerative farming, mangroves, and circular waste systems.
GreenMolecules become currency, not concepts
By YR2040, Europe will need:
1) 20–30 million tonnes of greenhydrogen
2) 6–8 million tonnes of greenammonia
3) 45–60 million tonnes of sustainableaviationfuels
4) Renewable gas pipelines that replace fossil molecules
Energy trade is no longer geography.
It is chemistry.
Carbon becomes the new KPI in boardrooms
Profit will still matter.But profit per tonne of emissions will matter more.
Companies that move early will enjoy:
lower capital cost, easier global market access, premium pricing, investor trust, regulatory goodwill
BusinessTrends That Will Break the Old Playbook
✔ Supply chains reorganise around emissions, not cost
Europe will buy from the cleanest supplier, not the cheapest.
✔ Green-collar skills become the new gold
From hydrogen technicians to carbon-accounting analysts
talent pivots to climate competence.
✔ Climate transparency becomes a brand’s survival kit
A label without carbon truth will look outdated.
Greenwashing will become commercial suicide.
✔ Investments flood into clean-tech
Hydrogen, e-fuels, biofuels, storage, grid digitalisation —
These aren’t sectors anymore.
They’re growth engines.
✔ Heavy industry enters its reinvention decade
Steel, cement, fertilisers, plastics, mobility they must rebuild their chemical DNA.
This is nothing short of Industrial Renaissance 2.0.
Europe didn’t set a target.
It set a tempo —
and the rest of the world must now adjust its rhythm or fall behind.” Dr. Anju Sharma
This is the decade when
carbon competence = business relevance
and
climate ambition = competitive advantage.
MrsSustainability | KtalystInsights)
Originally published on LinkedIn on 2025-11-16 20:27:34: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A14627700-7395920490277625856
♻️ PlasticRecycling: TheSilentBillionDollarRevolution
isn’t just saving waste — it’s reshaping economies.
Discover the real market movers with KtalystInsights.
#♻️ “Recycling isn’t just renewal; it’s reinvention. Every plastic reimagined is a future reclaimed.” — KtalystKeystone
GlobalLandscape
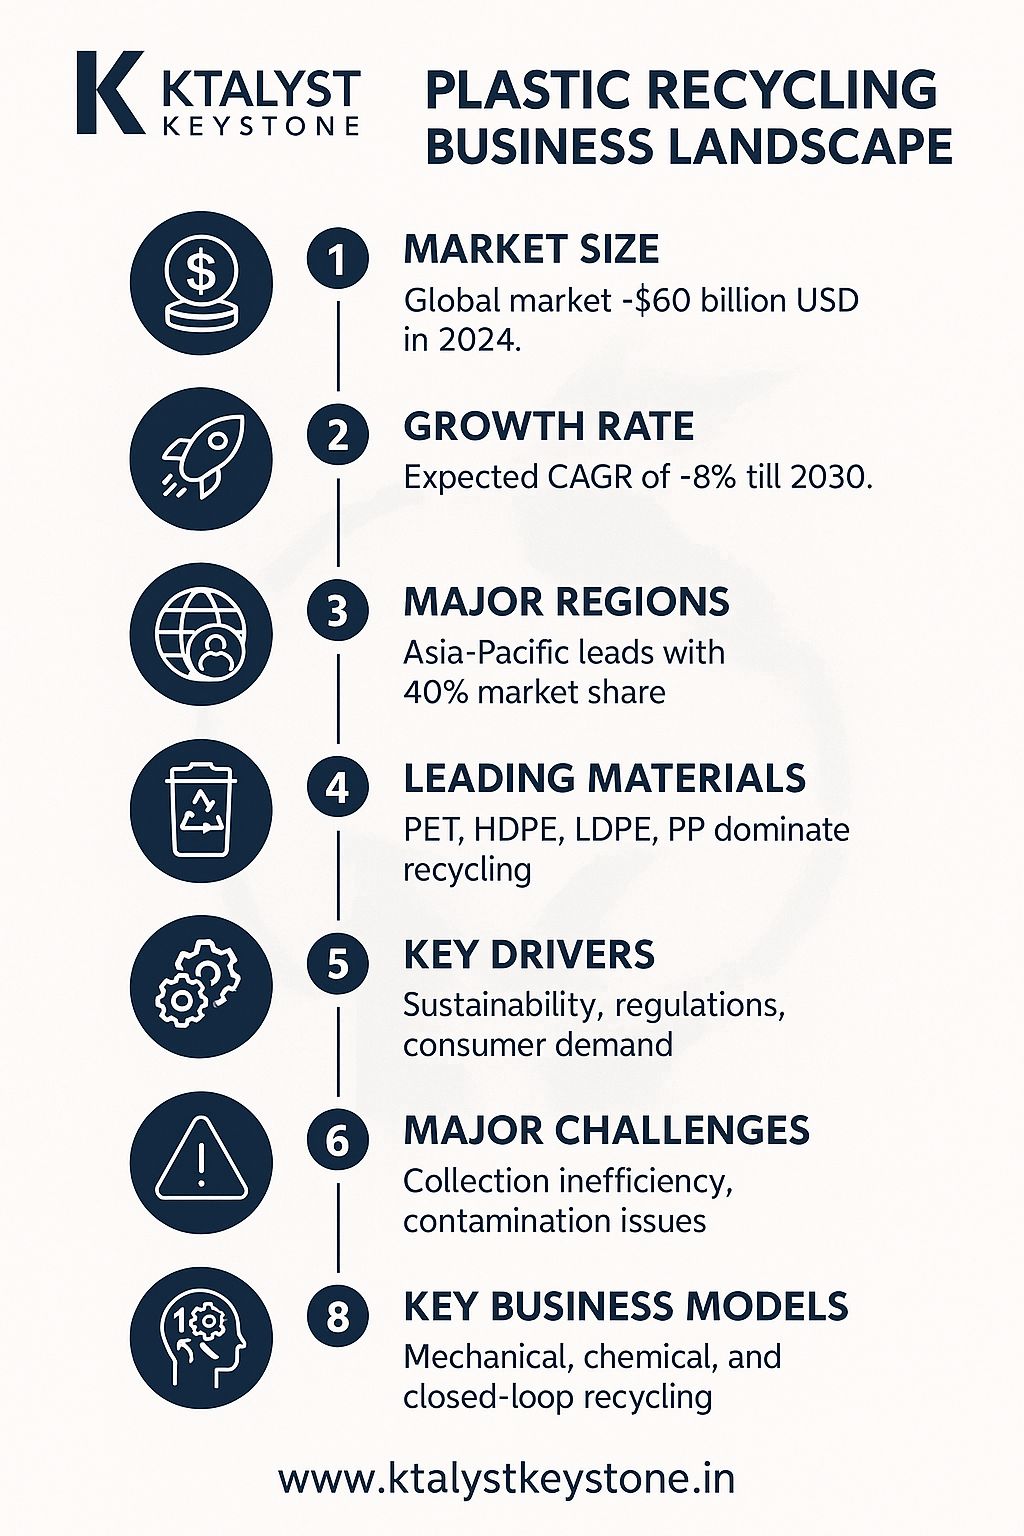
🌎 MarketSize (2024): ~$60 billion USD
📈 ExpectedCAGR (2024–2030): ~8%
🗺️ TopRegions:
AsiaPacific (~40% share)
Europe (~25%)
NorthAmerica (~20%)
KtalystInsight:
Asia’s dominance is fueled by aggressive policyshifts (China’s Green Fence, India’s EPR regulations) — local recycling startups and global joint ventures are booming.
KtalystRecyclingRating
⭐ AsiaPacific: 8.5/10 — Rapid growth, moderate tech.
⭐ Europe: 9.2/10 — High regulation, tech leadership.
⭐ NorthAmerica: 8.0/10 — Innovation-led recycling but slower mass adoption.
⭐ LATAM & Africa: 5.5/10 — Emerging opportunity zones with infra gaps.
KtalystInsight:
Europe sets the goldstandard with circulareconomy laws, while Asia leads in volume but needs advanced tech and traceability upgrades.
5KeyApplications
🛍️ Packaging – Bottles, containers, films (PET, HDPE).
👕 Textiles – Recycled polyester for apparel and furnishings.
🚗 Automotive – Lightweight components from recycled PP and composites.
🏗️ Construction – Pipes, panels, roofing from recycled plastics.
🎮 ConsumerGoods – Toys, gadgets, daily-use products.
KtalystInsight:
Packaging & Textiles together consume over 60% of all recycled plastics — brands chasing ESG targets are pivoting toward 100% recycled content.
FuturePotential
⚙️ AdvancedRecyclingTech (ChemicalRecycling): Unlocking hard-to-recycle plastics.
🤖 AIandRobotics: Smart sorting tech increasing plant yields by 25–30%.
🌿 BioplasticsHybridization: Next-gen materials mixing recycled polymers with bio-based resins.
KtalystInsight:
MechanicalRecycling dominates today, but ChemicalRecycling will be the investmentmagnet for the next decade, especially in Asia and the US, driven by stricter EPR mandates.
FinalThought
The PlasticRecycling economy is no longer a side act.
It’s the next trilliondollaropportunity, the ESGcredibility anchor, and a critical climatestrategy.
At KtalystKeystone, we believe recycling is no longer optional; it’s industrialevolution.
Originally published on LinkedIn on 2025-04-27 11:21:36: https://www.linkedin.com/feed/update/urn%3Ali%3AugcPost%3A7322218357754081280

