🔗💥 SteelTheFuture: Who’s Forging What—and When?
KtalystInsights | GreenSteel | SmartSteel | India2030 | NetZeroTargets
Tonnage builds today. Partnerships + NetZero paths build tomorrow.
Ktalyst Keystone
India’s steelmakers are recasting legacy with climate-smart ambition.
🌍 Net Zero targets and 🤝 global alliances are now the true currency of competitiveness.
📊 SteelScorecard2025
Net Zero Timelines | Big-Name JVs | Future Readiness
🏭 Tata Steel
🎯 2045 (India) / 2050 (Group)
Nippon, thyssenkrupp, ABB, SMS, NYK
🏭 JSW Steel
🎯 2050
POSCO, IIT-Bombay, Shield AI
🏭 SAIL
🎯 2070 (GoI-aligned)
NTPC, ABB, John Cockerill, Mjunction
🏭 JSPL
🎯 2047
GreenLine, Indian Coast Guard, Renewables
🏭 AM/NS India
🎯 2050
Nippon, Greenko, IBM, NSDC
🏭 ArcelorMittal
🎯 2050 (Global)
Schneider, Breakthrough Energy, HP
🏭 POSCO
🎯 2050
Hyundai, Honda, JERA, JSW
📌 KtalystInsights: Infographic Highlights
🔹 India’s Net Zero Steel Clock is Ticking:
> From 2045 to 2070—each year counts in climate competitiveness.
🔹 JVs Are the New Foundries:
> Strategic partnerships are replacing old smoke stacks—think hydrogen, AI, and digital twins.
🔹 Hydrogen Is No Longer Hype:
> JSPL, AM/NS, and POSCO are putting green hydrogen at the heart of steelmaking.
🔹 Smart Steel = Smart Collaborations:
> From ABB and IBM to IITs and Schneider, tech is now the hottest alloy.
🔹 Execution Over MoUs:
> Signed papers don’t cut carbon—real decarbonisation needs capital deployment.
Originally published on LinkedIn on 2025-07-02 17:44:56: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A82951-7346232425460445184
💡 KtalystInsights – GreenHydrogenExports?
Projects till date 250announced
Operation less than 10percent or revenue-generating.
India is promising but small-scale.
Australia & UK have paused projects due to infra issues.
MiddleEast is building—but for exports, not domestic decarbonisation.
China is overproducing electrolyzers, not hydrogen.
GreenHydrogen: Big Bets, Blunt Realities & Billions at Stake
🔍 “When decarbonisation dreams meet deployment delays.” — KtalystInsights
📊 H1_2025 Global Snapshot – What’s Hot, What’s Not
🌍 Region 💡 Progress 💸 Investment (USD) ❌ Reality Check with Timeline
🇮🇳 India GST proposed: 18% ➡️ 5% on green H₂ Policy incentive ⏳ Draft policy under review – rollout expected Q3 2025
🇮🇳 India Adani’s 5 MW off-grid plant live (Gujarat) ~$6.5M ⏳ Commissioned, but commercial offtake undefined till mid-2026
🇮🇳 India Greenzo wins ₹320 Cr (~$38.5M) EPC order Private project with Oswal ⏳ Project groundwork begins late 2025; output expected mid-2027
🇮🇳 India Toyota + Ohmium microgrid pilot Strategic collaboration ⏳ Pilot in Q2 2025, scalability assessment due early 2026
🇦🇺 Australia Fortescue’s Gladstone H₂ plant paused $650M on hold ⏳ Paused indefinitely; next review Q4 2025
🇦🇺 Australia NSW Hydrogen Hubs get AUD 100M (~$67M) federal grant Policy grant ⏳ Infra permits delayed; construction pushed to 2026
🇪🇺 EU €1B Hydrogen Bank funds 15 projects ~$1.08B ⏳ First rollouts begin late 2025, full ramp by 2027
🇨🇳 China Electrolyzer orders 2025 > 2024 total >$500M ⏳ Plants built; idle capacity reported in Q1 2025
🇺🇸 USA Trump’s 45V subsidy shortened ~$40B investment risk ⏳ Credits expire sooner (by 2027); FIDs slowing Q2 2025
🇬🇧 UK SSE & Equinor pause Keadby H₂ project $100M project paused ⏳ Review delayed till 2026, pending cost benefit clarity
🇮🇹 Italy Edison-Italgas blend 20% green H₂ in Sardinia <$5M pilot ⏳ Testing ends Q3 2025; national scale-up unclear
🇨🇦 Canada HyVera launches mobile Indigenous green H₂ <$2M seed ⏳ Deployed in BC, Alberta rollout planned Q1 2026
🇸🇦 SaudiArabia NEOM’s 4 GW green H₂ under construction $8.4B total CAPEX ⏳ Phase-1 exports via ammonia from late 2026 onward
🇦🇪 UAE ADNOC signs green ammonia deals with Japan, Germany ~$3B MoUs signed ⏳ Exports planned 2027; domestic use still in infancy
📉 Green H₂ Economics – The Hard Math (2025)
💰 Green H₂ cost: $3–$6/kg vs Grey H₂: ~$1/kg
⚙️ Electrolyzer CAPEX: $1.2–1.5M per MW
🎯 Global parity goal: $1.5/kg by 2030 → Needs $300B+ investment
⏳ Timeline truth: The real hydrogen economy won’t arrive before late 2026–2028. Until then, it’s pilot mode + policy prep.
💬 Your take:
Is green hydrogen a sunrise sector—or a sunrise stuck in traffic?
GreenHydrogen KtalystInsights Hydrogen2025 EnergyTransition India2030 MiddleEastEnergy PolicyToProfit CleanTechWatch GlobalHydrogenWatch NamasteIndia
Originally published on LinkedIn on 2025-06-27 04:57:49: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7344227431928553474
🌍 NamasteIndia’s Emerging 2025TrendsGreenTechOutlook 🇮🇳
From coastal corridors to global climate leadership, India is positioning itself as a hub for green hydrogen, ammonia, and clean energy exports.
📌 Key Trend: GreenHydrogen is not just a domestic ambition—it’s India’s new global growth story.
🔹 Top India-HQ Players Leading the Shift:
1. AMGreen – Launches the Kakinada green ammonia project (0.5–1 MTPA), with plans to supply 20% of Europe’s green ammonia by YR2030.
2. Reliance – GigaScale hydrogen from Jamnagar.
3. AdaniGreen – Scaling from 13.48 GW to 45 GW of renewables by 2030, driving integrated hydrogen-ammonia systems.
4. BPCL & LarsenToubro – Building electrolyzers, mobility hubs, and infrastructure from Kochi to Mundra.
5. NTPCGreen – Powering public-sector scale, with targets of 100,000 tonnes/year of green hydrogen.
6. Startups – Log 9 Materials and Green Trek are pioneering graphene fuel cells and sustainable steel.
📈 Emerging 2025Trends:
✅ Export-first ammonia & hydrogen corridors to Europe, Japan, and Singapore
✅ Indigenous electrolyzer manufacturing reducing costs by 30%
✅ Sector-wide decarbonization across fertilizers, aviation, and shipping
✅ Startup and public-private collaboration shaping India’s green edge
🔎 What’s Driving It:
📊 India’s green hydrogen market projected at $8B by YR2030!
🏛️ NationalGreenHydrogen Mission ($2.4B) + PLI schemes + global MOUs
🌞 Lowest solar costs globally (~$0.03/kWh), making green fuels viable
💬 India’s GenZ workforce, global investors, and policy leaders are aligning with one goal: Sustainable growth, exported at scale.
📢 What should India prioritize next—electrolyzer R&D, green steel, or global alliances?
Originally published on LinkedIn on 2025-05-28 11:39:24: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7333456858675867648
India’s Sustainability Surge
KtalystKeystone Insights | 2024–2025
🌱 Is India sprinting toward sustainability—or pacing for a marathon?
Here’s your crisp decode from Ktalyst Keystone Consulting—where we map markets to spark solutions.
KeyWins:
SolarPower: India ranks 3rd globally with 100+ GW capacity—overtaking Japan
Reforestation: World’s largest Miyawaki forest takes root in Kutch, Gujarat
GreenHydrogen: National Mission powers MSME clean energy transformation
ClimateFinance: India calls for $1.3T annual climate funding by 2035 under BRICS
GapsToWatch:
Only 2% of consumers willing to pay premium for sustainable products
CircularEconomy remains slow—policy-to-practice gaps persist
Patchy adoption in sectors like SustainableTourism
KtalystViewpoint:
Data is only half the story—insight drives impact.
Tap into our latest infographic to decode where India’s green journey shines… and where it stalls.
Ready to lead sustainably?
Explore the full landscape with us
📊 [Link to infographic or website]
Sustainability India2030 GreenHydrogen ClimateAction SDGs CleanEnergy KtalystKeystone MarketMapping ESG NetZero SustainableIndia
Originally published on LinkedIn on 2025-05-09 16:41:06: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A2474261-7326647415095091200
Biogas Boom: Why Investors Are Finally Paying Attention
KtalystKeystone Insight
Biogas is India’s triple-bottom-line jackpot—cutting imports, clearing waste, and creating jobs. When cow dung turns into cash flow, you’re not chasing a trend—you’re investing in a revolution.
FromPolicyToProfit — this sector is heating up. Here’s why:
MarketSize: Growing from USD 1.77B (₹14,750 Cr) in 2025 to USD 3.49B (₹29,000 Cr) by 2032.
RecentDeals:
₹200 Cr (USD 24M) committed at RenewX 2025.
₹1,600 Cr (USD 192M) lined up at REI Expo 2024.
CorporateMoves:
Maruti Suzuki investing ₹450 Cr (USD 54M) into renewables (including a biogas pilot at Manesar).
GovernmentPush:
SATAT aims for 5,000 CBG plants generating 15 MMT/year.
Up to ₹10 Cr (USD 1.2M) in Central Financial Assistance per project.
ESGReady: Aligned with carbon credit markets + GHG offset metrics.
WasteToWealth: Over 700 MMT of waste = fuel, fertiliser, and financials.
GloballySpeaking — Biogas is Booming Too
GlobalMarket: Expected to hit USD 88.79B by 2025 (CAGR 8.1%).
USLead: USD 3B in 2024 investments, 125+ new plants.
EuropePlays: Ørsted invests USD 30M in new biogas assets.
KtalystTake: Sunrise Sector Checklist
EnergySecurity ✔
DecentralisedInfra ✔
RuralLivelihoods ✔
CarbonRevenue ✔
GlobalValidation ✔
Don’tWait — the shift from stubble-burning to sustainable earnings is already underway.
https://lnkd.in/gQS673di
Download the TOI app now:
https://lnkd.in/dZigKD2s
Originally published on LinkedIn on 2025-05-02 14:50:24: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7324082840797687811
IndiaAtCOP26: Are We Walking the Talk — or Just Talking the Talk?
You cannot greenwash a deadline. Climate targets don’t wait, and neither should leadership.
Anju Sharma
In 2021, India made a powerful promise to the planet.
By 2025, the applause has faded. It’s time for accountability — not just ambition.
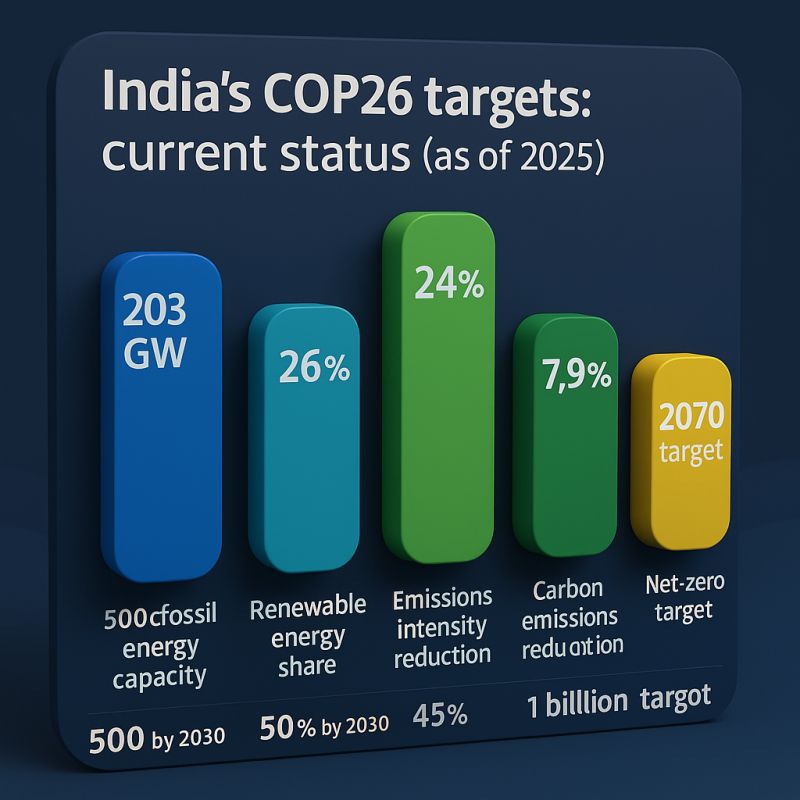
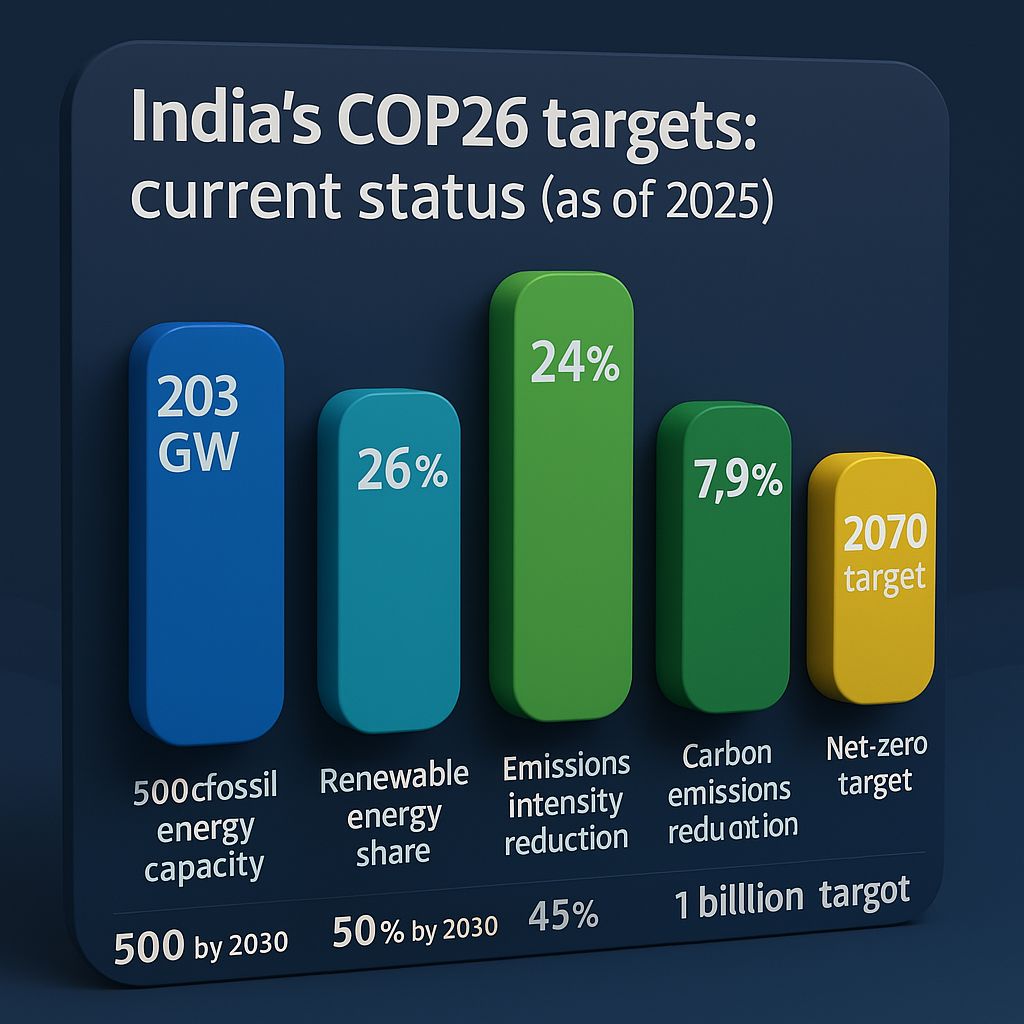
The 5Targets. The 5Year Reality Check:
🔋 500 GW Non-Fossil Energy by 2030
✅ 203.18 GW achieved (as of Oct 2024)
⚠️ Slowing pace. Grid and land hurdles choking large projects.
⚡ 50% Power from Renewables
✅ 26% YoY growth in clean energy (Jan 2025)
⚠️ Rooftop solar under 15% of target. State policies? All over the place.
📉 45% Emission Intensity Cut by 2030
✅ 33% achieved
⚠️ Driven by GDP growth — not aggressive emissions management.
🌫️ 1 Billion Tonnes CO₂ Reduction by 2030
✅ 7.9% drop in 2020
⚠️ But coal production surged 9% in 2024. Net gains? Neutralized.
🕰️ Net-Zero by 2070
✅ Roadmap submitted.
⚠️ No sectoral mandates. No accountability. No serious momentum.
Where’s the Leadership?
🚫 Ministries in silos
🚫 Power sector still fossil-heavy
🚫 EV infra crawling
🚫 Agriculture untouched
Are we really driving the transition — or just riding a global narrative?
And the Money?
💰 India has raised billions — Green Bonds, FDI, PLI schemes…
But…
❌ Utilization = uneven
❌ Outcome tracking = missing
❌ Impact per rupee = unclear
The climate rupee has wings — but no flight path.
The Fix — And Fast
✅ Appoint sector-wise climate champions with KPIs
✅ Launch public climate spend dashboards (Geo-tagged)
✅ Train bureaucrats in ESG, climate finance & tech
✅ Incentivize state-wise performance on climate goals
At_This_Pace, Where_Will_We_Land?
⏳ 3/5 targets may be missed
⏳ Investor confidence may fade
⏳ India’s brand as a climate leader may turn into a paper tiger
India doesn’t lack ambition.
It lacks the fire to deliver.
Time to shift gears.
From policy promises to powerful performance.
Originally published on LinkedIn on 2025-03-30 11:31:32: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A4385073-7312073993270784000
GreenIsTheNewGrit
India’s Sustainability Shift in Fast-Forward
From bold emission norms to ESG disclosures, India’s journey toward sustainability is accelerating — on paper.
But as we move from intent to impact, it’s clear that what’s green in policy must also grow on the ground.
#”India’s sustainability canvas is filling up with bold strokes of intent. The frameworks are strong, the policies are in motion — but the art remains incomplete. The brush of execution still lags behind the vision.
Anju Sharma
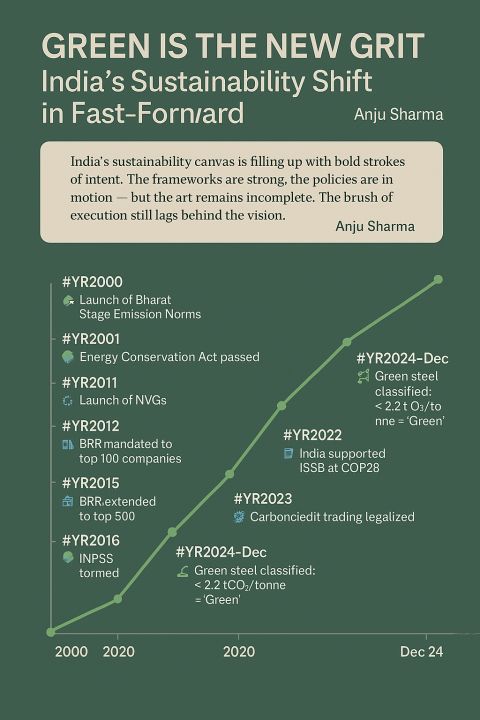
Here’s a quick snapshot of India’s evolving sustainability framework:
YR2000 [🚗] Bharat Stage Emission Norms introduced – India begins regulating vehicle pollution.
YR2001 [⚡] Energy Conservation Act passed – BEE is born.
YR2011 [♻️] ESG enters boardrooms with National Voluntary Guidelines (NVGs).
YR2012 [📊] Top 100 listed firms mandated to report sustainability via BRR.
YR2015 [🏢] BRR expanded to top 500 companies.
YR2016 [🌐] INPPSS launched with UN support.
YR2020 [🌬️] BS-VI norms enforced nationwide — leapfrogging clean air policies.
YR2021 [📃] India backs ISSB — for global ESG alignment.
YR2022 [💱] Carbon Credit Trading legalized.
YR2023 [🛢️] E20 ethanol-blended fuel launched.
[🧾] BRSR Core ESG reporting begins with top 150 companies.
YR2024-Dec
[🏗️] Green Steel classified: <2.2 tCO₂/tonne = Green
[✅] Eco-Mark expanded to 17 product categories
[☀️] Solar PV mandate issued – only Made-in-India cells allowed from June 2026.
What’s Next?
Time to match pace on execution. The clock is green. The momentum must be too.

Originally published on LinkedIn on 2025-03-30 05:39:36: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A1967292-7311985426058088448

