KtalystGreyToGreen: Shipping partner that strengthens your carbon credits, not your carbon liability.
Dr. Anju Sharma MrsSustainability
Scale built the old maritime advantage.
Scale minus carbon is building the new one.
EU ETS surrender obligations rise to 70% in 2026, after 40% in 2025, and move to 100% from 2027 onward for covered shipping emissions. Coverage already includes CO₂ and expands to CH₄ and N₂O from 2026. Carbon has moved from sustainability language to operating cost.
More than 80% of world trade by volume moves by sea. Shipping therefore sits at the center of a new commercial equation: freight rate, fuel choice, compliance cost, and carbon exposure now travel together.
1. Carbon has entered freight math
✓ EU ETS now applies to large ships of 5,000 GT and above calling at EU ports.
✓ Compliance rises in stages: 40% → 70% → 100%.
✓ Methane and nitrous oxide enter the system from 2026.
Shipping is no longer managing only fuel bills. Shipping is now managing carbon bills too.
2. Fuel choice has become strategy
✓ FuelEU Maritime is pushing demand toward renewable and low-carbon fuels.
✓ Zero-emission technology at berth is part of the transition logic.
✓ Fleet relevance now depends on fuel optionality, not only vessel size.
3. Global direction is already set
✓ IMO’s 2023 GHG Strategy calls for at least a 40% reduction in carbon intensity by 2030.
✓ IMO also targets at least 5%, striving for 10%, uptake of zero- or near-zero-GHG fuels, technologies, and energy sources by 2030.
✓ Ships above 5,000 GT account for about 85% of international shipping GHG emissions, which is why regulation is focusing there.
4. Market leaders are already shaping the curve
Public Alphaliner data continues to place MSC, Maersk, CMA CGM, COSCO, and Hapag-Lloyd among the leading global liner operators. Fleet decisions by these carriers influence fuel pathways, ordering logic, and competitive benchmarks across the sector.
5. The Value edge is changing
Old shipping advantage: scale.
New shipping advantage: scale with lower carbon liability.
That means:
✓ lower ETS exposure
✓ better fuel optionality
✓ cleaner freight propositions for Scope 3-conscious customers
✓ stronger long-term asset relevance under tighter regulation
KtalystKlues™
A ship is no longer judged only by what it carries. A ship is increasingly judged by what it burns, emits, and leaves behind.
The voyage is the same.
The value equation is not.
Abrivations: TEU = twenty-foot equivalent unit | DWT = deadweight tonnage | EU ETS = European Union Emissions Trading System | IMO = International Maritime Organization | GHG = greenhouse gas | GT = gross tonnage | CO₂ = carbon dioxide | CH₄ = methane | N₂O = nitrous oxide
KtalystMarineGreens KtalystValueEdge KtalystGreyToGreen KtalystInsights™ KtalystKlues™ MrsSustainability
Originally published on LinkedIn on 2026-04-22 08:52:52: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7452640558793240576
🚀 “The 3Es of ₹Ethanol: Environment, Economy & Efficiency – Is India Getting It Right?” 🌱💰⚡
Fueling sustainability or fueling a crisis?
India’s EthanolBlending mission is racing toward 20% ethanol-petrol blending (E20) by 2025-26, aiming to slash ₹53,894 crore ($6.5B) in crude oil imports annually while cutting CO₂ emissions by 2.3 million tonnes—equivalent to taking 4.2 lakh cars off the road. (MoPNG, 2024) But does ethanol truly deliver on Environment, Economy, and Efficiency?
🌍 1. Environment: Green or Resource-Heavy?
✔️ CO₂ Reduction: Ethanol blending cut 2.3M tonnes of CO₂ in 2023, but its full lifecycle emissions remain debated. (MoPNG, 2024)
✔️ Water Crisis: Producing 1L of ethanol from sugarcane requires 2,860L of water, straining groundwater. (NITI Aayog, 2024)
✔️ Crop Dependency: 92% of India’s ethanol comes from sugarcane, a crop linked to declining soil fertility. (IEA, 2024)
✔️ Air Quality Gains: E20 reduces particulate matter by 30-50%, improving urban air pollution. (ICCT, 2024)
📌 RealityCheck: Can ethanol be truly sustainable when it risks food & water security?
💰 2. Economy: Cost Savings vs. Inflation?
✔️ Fuel Independence: Ethanol saved India $6.5B in oil imports in 2023. (MoPNG, 2024)
✔️ Investment Boom: The sector is attracting ₹41,000 crore ($4.9B) in new investments by 2025. (NITI Aayog, 2024)
✔️ Job Creation: Ethanol production has generated 4 lakh jobs in rural India. (MoPNG, 2024)
✔️ Food Price Spike: 40L tonnes of sugarcane & 25L tonnes of grain were diverted to ethanol in 2023, contributing to food inflation. (FAO, 2024)
📌 RealityCheck: Are we trading food security for fuel independence?
⚡ 3. Efficiency: Can Ethanol Compete with Petrol?
✔️ Mileage Drop: E20 reduces fuel efficiency by 6-10%, requiring more frequent refueling. (SIAM, 2024)
✔️ Vehicle Readiness: Only 20% of India’s petrol vehicles are E20-ready. (MoRTH, 2024)
✔️ Slow Adoption: Just 6% of fuel stations nationwide are E20-compliant. (BPCL, 2024)
✔️ Flex-Fuel Future: Maruti, Toyota & Honda have launched E85-compatible vehicles, but mass adoption is slow. (AutoCar India, 2024)
📌 RealityCheck: Can ethanol match petrol’s efficiency without major tech breakthroughs?
🇺🇸 US Interest in India’s Ethanol Push
🔹 Corn Exports: The US exported $1.2B worth of ethanol-friendly corn to India in 2023. (USDA, 2024)
🔹 Big Oil & Biofuels: ExxonMobil & Chevron have invested $800M in India’s ethanol supply chain. (Bloomberg, 2024)
🔹 Strategic Partnerships: US firms are eyeing India’s ₹41,000 crore ($4.9B) ethanol market for global expansion. (Reuters, 2024)
Originally published on LinkedIn on 2025-02-21 17:04:12: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A82951-7298749364091428865
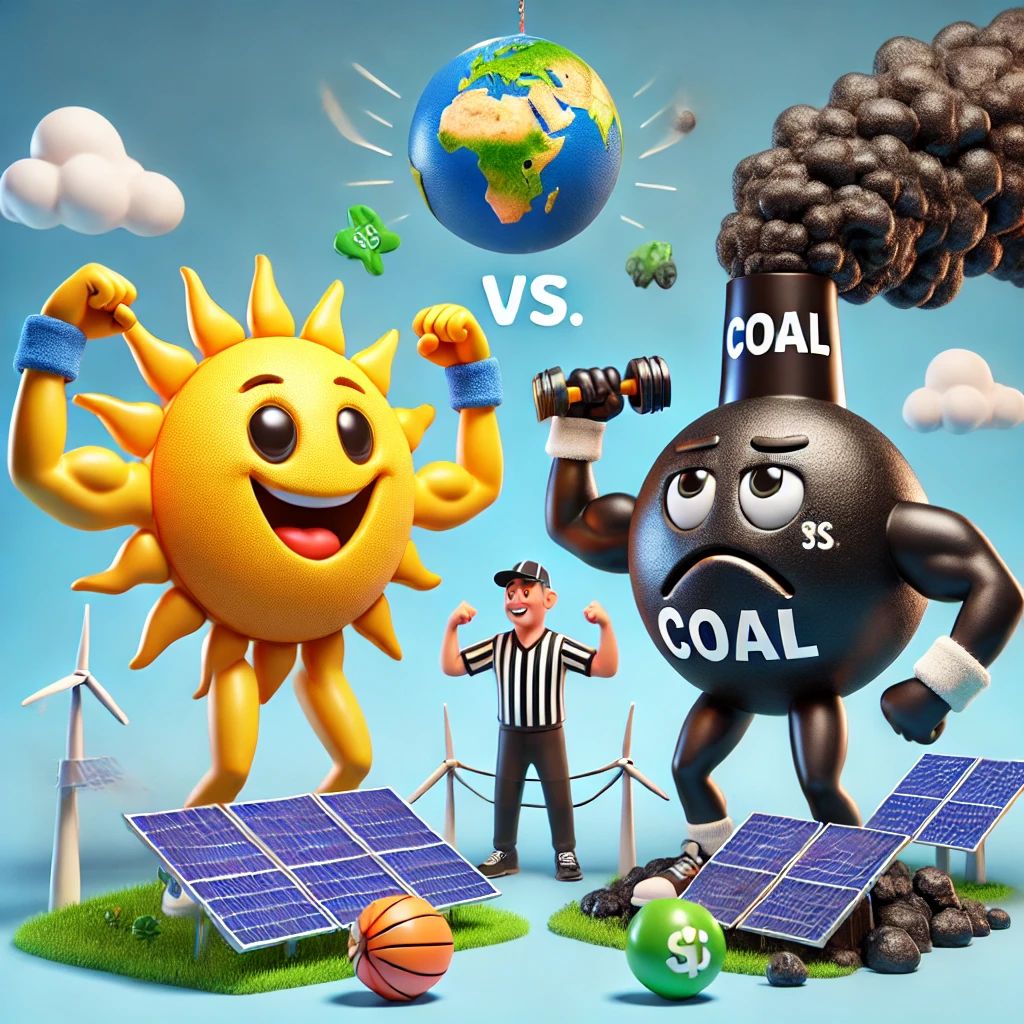
Solar vs. Coal: The USD10_Trillion Energy Disruption We Can’t Ignore” ☀️⚡🔥
Solar is cheaper, cleaner, and scaling fast, but can it fully replace coal? Here’s a data-driven breakdown of efficiency, cost, impact, and future trends.
🔍 Efficiency & Reliability
☀️ Solar – 15-22% efficiency, drops 80-90% at night. (Source: NREL, 2023)
🔥 Coal – 35-45% efficiency, generates 24/7 power. (Source: IEA, 2023)
🏆 Winner: Coal (for base-load power), Solar (for clean production).
💰 Cost & Scalability
☀️ Solar – #$25-$50 per MWh, 89% price drop since 2010. (Source: Lazard, 2023)
🔥 Coal – #$65-$150 per MWh, rising due to fuel costs & carbon taxes. (Source: IEA, 2023)
🏆 Winner: Solar (cheaper & getting cheaper).
🌍 Environmental Impact
☀️ Solar – Zero emissions, but 78M tons of solar waste by 2050. (Source: IRENA, 2023)
🔥 Coal – 820g CO₂ per kWh, highest among energy sources. (Source: IPCC, 2023)
🏆 Winner: Solar (cleaner, but needs better recycling).
🔋 Future Trends
✅ Solar Prices Falling – Expected 50% cheaper than coal by 2030. (Source: BloombergNEF, 2024)
✅ Coal Declining – 40% of coal plants to shut by 2040. (Source: IEA, 2023)
✅ Battery Breakthroughs – Solving solar’s intermittency problem.
🏆 Final Verdict: Solar ✅ (Cleaner, scalable, and cost-effective, but storage & recycling must improve).
KeyTakeaway
Solar is already outcompeting coal, but its future depends on energy storage & recycling innovations. The transition is happening—the only question is how fast.
👉 Will solar dominate, or does coal still have a future?
SolarVsCoal CleanEnergy Sustainability EnergyEfficiency FutureOfEnergy
Originally published on LinkedIn on 2025-01-28 11:16:10: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A10334500-7289964467918983170
NamasteGreenIndia’s Ethanol Revolution: Achieving 20% Blending with a Sustainable Edge
India is on the brink of achieving a 20% ethanol blending target, a transformative step towards energy independence, environmental sustainability, and agricultural empowerment. Here’s how this revolution is shaping up:
📈 The Progress So Far
🟢 2014: Ethanol blending in petrol was just 1.53%.
🟢 2024: Achieved 15%, with 4.62 million metric tonnes (MMT) of ethanol produced.
🟢 2025 Target: Projected to produce 10.2 MMT annually to meet blending and industrial needs.
🌍 Economic & Environmental Wins
💰 USD 4 Billion Saved: Annual savings on crude oil imports.
🌎 10 MMT CO₂ Reduced: Emissions cut significantly with 20% ethanol blending.
👷 500,000 Jobs Created: Boosting rural employment through distilleries and supply chains.
🚢 USD 300 Million Export Potential: Surplus ethanol positioned for international markets.
🚗 Automotive Industry’s Ethanol Push
🔧 Flex-Fuel Vehicles: Tata Motors, Mahindra, Maruti Suzuki, and Hyundai to launch 100% bio-ethanol vehicles within six months.
🛢️ Fossil Fuel Demand Cut: Flex-fuel vehicles to reduce reliance on fossil fuels by 5.5 MMT annually.
🏭 Toyota’s Commitment: Investing ₹20,000 crore (USD 2.4 billion) in ethanol-compatible vehicle production.
🌾 Agricultural Boost
🌱 8-9 MMT of Sugar: Diverted annually for ethanol production, stabilizing prices and supporting farmers.
🌾 1.5 MMT of Surplus Grains: Utilized for ethanol, ensuring sustainable revenue for agriculture.
⚡ Challenges & Opportunities
📊 Feedstock Demand: India needs an additional 2 MMT of sugarcane and 1.5 MMT of surplus grains for sustainable production.
🏗️ Infrastructure Gaps: Only 30% of fuel pumps are ready for E20 blending.
🌍 Global Leadership: Scaling production and refining distribution could position India as a leader in ethanol exports.
💡 Why This Matters
India’s ethanol revolution is more than a blending target—it’s about energy self-reliance, cutting carbon footprints, and empowering rural economies. This initiative showcases India as a global benchmark for sustainable energy transitions.
💬 Let’s discuss how India’sEthanolJourney is driving SustainableEnergy, AutomotiveInnovation, and RuralEmpowerment! 🚀
Originally published on LinkedIn on 2025-01-16 09:51:29: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A12538632-7285594503120347137
YR2024_India’s Bioenergy Capacity Hits New Milestone
India has reached a significant milestone in its clean energy efforts, with bioenergy playing a key role in the renewable energy mix. As of 13th November_2024, bioenergy contributes significantly to India’s renewable portfolio, supporting the country’s transition toward net-zero emissions by 2070.
With advancements in biogas, bioethanol, bio_CNG, and biomass power, India is accelerating its clean energy goals:
Bioenergy (~6%) now forms a critical part of the 46.3% renewable energy share in the total installed power capacity.
The sector supports decarbonization in transportation, industry, and aviation through initiatives like bioethanol blending and Sustainable Aviation Fuel (SAF).
India’s bioenergy growth reflects its focus on reducing fossil fuel dependency while strengthening its $20 billion bioeconomy, creating a sustainable and greener energy future.
India’s Bioenergy Partnerships in 2024
✅ TruAlt Bioenergy & Sumitomo Corporation
Focus: Biogas, Bioethanol, SAF
Target: Cutting fossil fuel dependency by 50%.
✅ ISMA, TERI & Praj Industries
Focus: SAF, Green Hydrogen
Target: 12 billion liters SAF annually by 2030.
✅ India_Brazil SAF Collaboration
Focus: SAF Supply Chain Optimization
✅ BPCL ($170M Investment)
Focus: SAF Production
Target: 5% SAF blending by 2030.
✅ IOC & LanzaJet
Focus: Waste-to-Ethanol SAF
Output: 80,000 metric tons annually.
✅ GPS Renewables & SAF One
Focus: Aviation Emission Reduction (8% GHG emissions).
✅ Adani Total Gas & Greenko Group
Focus: Biogas, Green Hydrogen
Impact: 10% reduction in industrial emissions by 2035.
✅ Reliance & Air Products
Focus: Bioethanol, SAF
Strengthening the $20 billion bioeconomy.
✅ Tata Power & Shell India
Focus: Bio-CNG, Biogas
Target: 5M metric tons annually by 2030.
✅ NTPC & Honeywell International
Focus: Green Methanol, SAF
Emissions Reduction: 20% by 2035.
✅ Vedanta & EcoEnergy Europe
Focus: Waste-to-Bioethanol
Target: 20% ethanol blending by 2025.
✅ L&T & Siemens Energy
Focus: Biohydrogen
Target: 1M metric tons annually by 2030.
Why This Matters
India’s bioenergy partnerships are driving innovation, emissions reduction, and economic growth.
📊 Key Stats:
50% fossil fuel dependency reduction by 2030.
12B liters SAF production annually by 2030.
20% ethanol blending by 2025.
5M metric tons of biogas production annually.
1M metric tons of biohydrogen by 2030.
India is laying the foundation for a sustainable and net-zero tomorrow, proving that collaboration is key to progress.
Source / shared link: https://pib.gov.in/PressReleaseIframePage.aspx?PRID=2073038
Originally published on LinkedIn on 2024-12-17 15:02:29: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A3880479-7274801133875822593
NamasteGreenIndia🌟 India’s Clean Energy Edge
📊 Key Statistics
$200B investment needed to achieve India’s renewable energy target of 500 GW by YR2030.
Solar capacity projected to rise from 70 GW to 280 GW by 2030.
Green hydrogen market in India expected to reach $44B by 2030, driven by projects from RIL, Adani, and ReNew Power.
India’s EV market forecasted to grow to $47B by 2030, requiring 4M EV chargers nationwide.
🔋 RIL’s Bold Vision for Green Energy
💰 $6B+ Invested in Clean Energy
Already deployed over half of its $10B budget to build a renewable energy ecosystem.
☀️ Solar at Scale
The 20 GW solar Giga factory in Jamnagar will commence production in phases starting March 2024 and reach full capacity by 2026.
🔋 BatteryPowerhouse
Developing a battery Giga factory for advanced storage and recycling solutions by 2026, addressing India’s growing energy storage needs (projected to hit 27 GW by YR2030).
💧 Green Hydrogen Revolution
Establishing a fully automated electrolyzer Giga factory, powering India’s green hydrogen production targets of 5 MTPA by YR2030.
⚡ Fuel Cell Innovation
Pioneering fuel cell technology, transforming hydrogen into power for commercial and industrial use, aligning with India’s commitment to net-zero by YR2070.
🤝 Strategic Acquisitions
Acquired REC Solar ($771M) and a 40% stake in Sterling & Wilson Renewable Energy ($240M) to strengthen its renewable portfolio.
📈 Profitability Meets Sustainability
Chairman Mukesh Ambani envisions the New Energy business matching the profitability of RIL’s oil-to-chemicals segment (which generated $35B in revenue in 2023) within 5-7 years.
🌏 Other Key Players Driving India’s Renewable Energy Revolution
🔹 TataPower
Committed to investing $9 billion to expand renewable capacity to 20 GW by YR2027.
Recently launched a 4.3 GW solar cell and module manufacturing plant in TamilNadu.
Partnering with the Tamil Nadu government to develop 10 GW renewable energy projects, with an estimated investment of $8.4 billion.
Operating 1.1 GW rooftop solar capacity and expanding EV infrastructure to install 50,000 charging points by 2030.
🔹 AdaniGreenEnergy
Operating 8 GW of renewable capacity and targeting 45 GW by YR2030.
Announced a $50B investment in green hydrogen, solar manufacturing, and wind projects over the next decade.
🔹 ReNew Power
Managing 13 GW operational capacity, targeting 25 GW by 2025.
Partnered with L&T and Indian Oil for green hydrogen projects, contributing to India’s $44B hydrogen market by 2030.
🔹 NTPC Limited
Targeting 60 GW renewable capacity by 2032, with large solar and wind projects in Rajasthan and Gujarat.
🔹 JSW Energy
Transitioning its portfolio to renewables, aiming for 20 GW capacity by 2030, up from its current 4.8 GW.
Originally published on LinkedIn on 2024-12-12 07:06:10: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A2635374-7272869323998679040
NamasteIndia just ahead of the COP29 Global GHG Emissions by Sector and Key Countries (2023)
Sector Breakdown
1. Power (26%, 15 Gt)
China (27%), US (11%), India (7%): Coal dominates emissions.
Focus: Transition to renewables and improve grid efficiency.
2. Transport (15%, 9 Gt)
US, China, EU: High emissions from vehicles and freight.
Focus: Expand EV adoption and public transport.
3. Industry (11%, 6 Gt)
China, India, US: Cement, steel, and chemical production.
Focus: Decarbonize processes with clean technology.
4. Fuel Production (10%, 6 Gt)
Russia, Middle East, US: Fossil fuel extraction.
Focus: Reduce methane leaks and shift to alternatives.
5. Agriculture (11%, 6 Gt)
Brazil, India, US: Methane from livestock, rice cultivation, and fertilizer.
Focus: Promote regenerative farming and reduce food waste.
6. Land Use & Forestry (7%, 4 Gt)
Brazil, Indonesia, Africa: Deforestation and land conversion.
Focus: Reforestation and sustainable land management.
7. Buildings (6%, 3 Gt)
US, China, EU: Energy use for heating and construction.
Focus: Energy-efficient buildings and renewable energy.
8. Waste (4%, 2 Gt)
India, China, US: Methane from landfills and wastewater.
Focus: Modernize waste management and capture methane.
Top Emitters
China (~30%): Coal, cement, and steel dominate.
US (~14%): Transport and energy-intensive sectors.
India (~7%): Power and agriculture emissions.
EU (~8%): Heavy industries and aging systems.
Brazil & Indonesia: Deforestation hotspots.
Global Priorities:
Energy: Expand renewables and phase out coal.
Transport: Scale up EVs and public transit.
Industry: Invest in clean production technologies.
Forestry: Halt deforestation and restore ecosystems.
Impact: Tailored, sector-specific strategies can drive significant reductions in global GHG emissions.
Source / shared link: https://www.visualcapitalist.com/charted-global-ghg-emissions-by-sector/
Originally published on LinkedIn on 2024-11-19 03:28:20: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A59930-7264479581858861056
Global Leaders in Ethanol Blending in Fuel: India’s Role and Achievements
NamasteIndia ranks among the top ethanol producers globally, alongside the US and Brazil. Tops Countries
1. US: The largest producer and consumer of ethanol, Production: 876K barrels Consumption 838K barrels per day.
2. Brazil: Produces 403K barrels per day and consumes 359K barrels per day.
3. China: Produces and consumes 43K barrels per day.
4. Canada: Produces 33K barrels per day; consumes 41K barrels per day.
5. France: Produces 17K barrels per day & consumes 13 thousand barrels per day.
6. Germany: Produces 13K barrels per day and consumes 27K barrels per day.
7. Colombia: 8.5K barrels/day (produces), 6.1K barrels/day (consumes).
8. Thailand: 8.1K barrels/day (produces), 9.1K barrels/day (consumes).
9. Guatemala: 8K barrels/day (produces).
10. Spain: 7.9K barrels/day (produces), 8K barrels/day (consumes).
11. Belgium: 6.8K barrels/day (produces), 1.8K barrels/day (consumes).
12. India: 5.3K barrels/day (produces & consumes).
13. Australia: 5.3K barrels/day (produces), 5.1K barrels/day (consumes).
14. UK: Produces 4.3 thousand barrels per day and consumes 17 thousand barrels per day.
India’s Ethanol Blending in Gasoline Industry
Key_Facts_&_Figures
Ethanol Blending Target: India aims to achieve 20% ethanol blending in gasoline by 2025, a goal accelerated from the original target of 2030.
Current Blending Level: As of May 2024, India has achieved a 15% ethanol blending rate.
Economic Impact: A successful ethanol blending program can save India approximately $4 billion (₹30K crore) annually by reducing oil imports.
Production Volume: India plans to produce around 10 billion liters (1,000 crore liters) of ethanol to meet the 20% blending target.
Role of Key Stakeholders
Government:
Policy Framework: The government has implemented policies like the National Policy on Biofuels.
Pricing and Incentives: The government administers ethanol prices and provides incentives to encourage production and blending.
Oil Marketing Companies (OMCs):
Procurement: OMCs issue annual tenders to procure ethanol from producers.
Blending and Distribution: OMCs blend ethanol with gasoline at designated depots and distribute the blended fuel to retail stations.
Sugar Industry:
Production: The sugar industry is a major producer of ethanol, utilizing by-products like molasses. Leading companies include Bajaj Hindusthan Sugar Ltd., Balrampur Chini Mills Ltd., Shree Renuka Sugars Ltd., and Dhampur Sugar Mills Ltd., contributing significantly to the total ethanol production.
Environmental impact: supports bioenergy production and waste utilization but also faces challenges like high water usage and pollution.
Originally published on LinkedIn on 2024-09-25 05:31:06: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A60128-7244579146016641026
NamastwAmbitiousIndia MukeshAmbani Unveils Ambitious Plans For New Energy Business With 5 Gigafactories Complex in Jamnagar:
Project Overview:
Location: Jamnagar, Gujarat, India
Complex Size: Over 5,000 acres
5_Gigafactories:
Types of Facilities:
Solar PV Panels
Advanced Energy Storage Batteries
Electrolysers
Fuel Cells
Power Electronics
Solar PV Panels:
Initial Production Q4_2024; 10 gigawatts (GW)
**Target Annual Capacity by_2030: 100 GW
Advanced Energy Storage Batteries**:
Annual Capacity: 30 gigawatt-hours (₹GWh)
Production Start: by_Q3_2025
Total Investment**: Approximately: $10 billion USD
Strategic Goals:
Net Carbon Zero Target: By_2035
Renewable Energy Sector Presence: Establish a significant footprint
Additional Details:
The complex will also focus on developing technologies for green hydrogen production and other renewable energy solutions.
These developments are part of Reliance’s broader strategy to transition towards sustainable energy and reduce carbon emissions.
https://lnkd.in/d6U7Bnmu
Originally published on LinkedIn on 2024-08-31 06:32:12: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7235534825695117313
Namaste Indian Sugar Mills Association (ISMA) has presented a forward-thinking plan to the government: **transform sugar mills into bio-refineries**. Here are the key points:
Objective: Boost production of sustainable aviation fuel and other green energy sources.
Policy Framework: ISMA representatives discussed this transition with Food Minister Pralhad Joshi.
Beyond Ethanol: The plan expands beyond current ethanol, bioelectricity, and biogas production.
International Goals: Aligns with international aviation blending targets (CORSIA mandates) for 2027.
Farmer Incomes: Aims to create alternative markets for India’s **55 million sugarcane farmers**.
Energy Security: Expected to set new benchmarks and strengthen India’s energy security.
Sugar industry body proposes bio-refinery transition plan to govt. https://lnkd.in/ddw3ZbJn.
Source / shared link: https://link.springer.com/article/10.1007/s12155-022-10406-4
Originally published on LinkedIn on 2024-07-26 19:27:42: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7222684023309893632

