NewGreed & CapitalFloats: Follow the money it’s wearing green!
Dr. Anju Sharma|MrsSustainability |KtalystInsights™
💚 GreenLove Shapes the Map, this isn’t romance. It’s money moving toward energysecurity, policycertainty, & sustainablemargins.
In the coming 3 years your sector matters more than your passport. That’s why the economy “RecoveryShapes” aren’t metaphors they’re capital diagnostics packed into one signal:
1️⃣ Growth speed
2️⃣ Margin strength
3️⃣ Capital concentration
➕ Policy-aligned capital flow (2026’s X-factor)
🇺🇸 UNITED STATES | K-Shape 📈📉
✓GDP: 2.1 → 2.4 → 2.0
✓S&P 500: Top 7 = 30%+ index weight
✓AI Capex (2025): $220B+
✓Productivity: +2% (’24–’25)
✅ AI, semis, infra = operating leverage vortex
❌ Regional banks, CRE = refinancing pressure
KtalystKlues™ :
Upper arm = multiple expansion ⚡
Lower arm = capital compression 💸
Capital isn’t spreading. It’s concentrating. No healthy for voters.
🇪🇺 EURO AREA | U-Shape 🐢
✓GDP: 1.3 → 1.4 → 1.4
✓Inflation: ~2%
✓Energy imports: 55% dependent
✓Industrial output: <2019 trend
✅ Stability improving
❌ Growth softening
KtalystKlues™: Defensive capital rules. Low volatility > high beta.
🇩🇪 GERMANY | L → U 🕯️
✓GDP: 0.2 → 1.1 → 1.5
✓Industrial output: –5% vs 2019
✓Energy cost: structurally high
✅ Fiscal impulse rising
❌ Competitiveness reset underway
KtalystKlues™ : Repricing cycle live. Selectivity = alpha.
🇨🇳 CHINA | W / K 🎢
✓GDP: 5.0 → 4.5 → 4.0
✓Property drag: ~25% of GDP
✓Solar exports: 60% global share
✓EV exports: 1 globally
✅ Green + industrial dominance
❌ Domestic cleanup incomplete
KtalystKlues™ Sector sharpness > macro optimism.
🇮🇳 NamasteINDIA | V → U 🚀
✓GDP (FY): 7.3 → 6.4 → 6.4
✓Public Capex: ₹11T+ ($130B)
✓UPI (Dec ’25): 21.6B txns | ₹28L Cr ($337B)
✓Renewables: 30–50 GW/year
✅ Fastest large economy
✅ Infra + digital stack compounding
❌ Execution > demand risk
KtalystKlues™: Growth is abundant. Governance determines margin durability.
🇯🇵 JAPAN | L ☁️
GDP: 1.1 → 0.7 → 0.6
Debt/GDP: ~250%
Workforce: shrinking
✅ Policy steady
❌ Trend growth fading
KtalystKlues™: Yield + preservation.
💡 KtalystInsight™
TheDecade unfolds = divergence in 4D:
🇺🇸 Productivity concentration
🇪🇺 Stability premium
🇨🇳 Industrial power + property drag
🇮🇳 Execution-filtered growth
🇯🇵 Stability plateau
Leadership question:
Are you compounding on the upper arm of the K or defending on the lower?
Because in this cycle:
Sector > geography
Energy > narrative
Execution > noise
Capital discipline > headlines
And here’s the doctrine:
Margins move where energy, policy, and execution align. Sector decides speed. Discipline decides survival.
Dr. Anju Sharma
Originally published on LinkedIn on 2026-02-18 05:15:59: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A1910576-7429755541888892928
Davos_Is_No_Longer_a_Summit.
It’s a Stress Test.**
Dr. Anju Sharma | KtalystInsights™ | Davos2026 (19–23 January 2026)
Every January, the world arrives in the Alps seeking answers.
In reality, Davos is a load test to see what bends, what holds, and what quietly recalibrates.
As Davos 2026 unfolds, one thing is becoming clear:
this is less about consensus and more about friction mapping.
🔍 Davos as a DiagnosticScan
A full-body MRI of the global economy.
✔ ~3,000 leaders | 130+ countries
✔ ~400 policymakers | ~64–65 Heads of State
✔ ~850 CEOs & Chairs
✔ 200+ sessions
✔ Narrative shift detected: Dialogue (theme) vs. Geoeconomic Confrontation (reality)
🌈Davos as a BalanceSheet
Strip the snow. It’s pure accounting.
✔ Swiss security deployment cap: ₹320 cr), locked till 2027
✔ Actual 2025 spend: ~CHF 24.6M
✔ World Economic Forum revenue (FY 2024–25): ~CHF 469M
❌ Profit motive (designed to preserve trust, not generate surplus)
🚀 Davos as a DealFilter
Presence doesn’t create value. Preparedness does.
NamasteIndia
✔ Uttar Pradesh delegation outcomes (confirmed Jan 20)
✔ ₹9,750 cr MoUs signed
✔ Clean energy | AI infrastructure | Defence
✔ Sub-national execution outpaced multilateral alignment
⚠️ Davos as a Risk RePricing Desk
The quietest shift is the most strategic.
✔ Geoeconomic Confrontation ranked 1 global risk (Global Risks Report 2026)
❌ Armed conflict as the top risk
✔ Tariffs, carbon borders, trade & tech controls as new conflict tools
🔳Davos as a Whiteboard (Not a Courtroom)
Ideas drawn. Commitments deferred.
❌ Binding global treaties
❌ Unified AI governance framework
❌ Executable global climate mechanism
🧭 KtalystInsights™ | Emerging Mid-Summit Take
✔ Attendance: record high
❌ Alignment: structurally low
✔ Hedging behaviour: everywhere
Davos2026 is actively confirming an era of Fragmented Togetherness.
Davos is no longer about fixing the world in four days.
✔ It is about calibrating strategy before volatility hardens into policy.
✔ Those here for optics are collecting photographs
✔ Those here for signal are recalibrating capital, supply chains, and risk
Attendance is not alignment.
Presence is not commitment.
In Davos, only prepared capital converts conversation into outcomes.”— Dr. Anju Sharma
KtalystInsights™ | MrsSustainability DataComa
Davos2026 GlobalRisks2026 GeoeconomicConfrontation LeadershipSignals
Originally published on LinkedIn on 2026-01-20 01:56:38: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7419196123795345408
🌍 COP30_COPingClimate? IgnoringTheEarthThermometer
COP30 didn’t divide the world.
It revealed how divided the world already is.
The planet’s thermometer sits at ~1.3°C, but countries still read it like different weather forecasts shaped by energy security, growth pressures, and political survival.
Climate summits don’t fail because science is unclear.
They fail because nations negotiate with their fears first,
and the planet second.” — KtalystInsights
The_GLOBAL_Mismatch — Physics vs Politics
✓ Warming ~1.3°C
✓ Climate disasters $250–300B/year
✓ Fossil subsidies ≈$1.8T/year
✓ Adaptation gap $215–387B/year
✓ Loss & Damage need ~$400B/year
✓ <40% aligned with 1.5°C
Clarity: The crisis is not technology.
It’s misaligned incentives.
KtalystInsights: Physics is fixed. Politics is fluid.
EU — Ambition With an Energy Allergy
✓ –90% by 2040
✓ Needs €300–400B/year
✓ 80–90% mineral imports
✓ Winter grid gas-anchored
✓ Refused fossil phase-out
Clarity: You can’t sign what your grid can’t survive.
KtalystInsights: A climate Ferrari on a fragile fuel line.
NamasteIndia — Justice in Numbers
✓ 50% non-fossil achieved
✓ 1.9 tCO₂ per capita vs 4.7 global
✓ Demand ~2× by 2040
✓ Coal = stability
✓ Seeks tech + concessional finance
Clarity: Not refusal — mathematical realism.
China — Maximum Speed, Minimum Shock
✓ 31% global CO₂
✓ ~300 GW solar in 2024
✓ 50% global renewables
✓ Coal 4.5–4.8B t
✓ Peak pre-2030
Clarity: No destabilising the factory of the world.
Brazil — Nature as Infrastructure
✓ Amazon deforestation –50%
✓ Grid 87–88% renewable
✓ Leading Article 6
✓ Forest-finance tools
Clarity: Monetising protection, not extraction.
Small Island States — Survival by the Decimal
✓ Emit 0.6%
✓ Extreme losses
✓ Need ~$400B/year
✓ Demand fossil phase-out
Clarity: 1.5°C = border security.
FossilEconomies — Revenue Before Rhetoric
✓ 30–60% revenue from hydrocarbons
✓ CCUS 300–435 Mt vs ~5000 needed
Clarity: Revenue cannot vanish faster than alternatives appear.
US — The Walkout That Tilted the Room
✓ 13–14% CO₂
✓ 1 oil & gas
✓ IRA $370B
✓ Walked out of COP30
Clarity: When the biggest player leaves, ceilings drop.
The thermometer is the only negotiator that doesn’t compromise.
When ambition finally meets energy reality,
the temperature curve will bend.” — Dr. Anju Sharma
Originally published on LinkedIn on 2025-11-22 17:06:17: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A82951-7398044162559930369
CostHavens to CapabilityEngines: The GCC/GSB Revolution
USD_128_billion & counting, that’s not the GDP of a small country it’s the market size of Global Capability Centers (GCCs¹).
NamasteIndia, with it’s 1,900+ centers and ~2 million professionals, is at the epicenter of this silent revolution.
NamasteIndia_Epicenter
1. ~1,900+ GCCs employ ~2 million people, contributing ~$60B today headed to ~$80B in 5 years.
2. Only 5% are “Mega GCCs” (>5,000 employees, $1B+ parent revenue), yet they house ~50% of India’s GCC talent.
3. Leading verticals: Telecom, Software, BFSI², Semiconductors, Healthcare.
4. 70+ more Mega GCCs are expected in India within the next 5 years.
GlobalTrends
1. Market size: $128B (2023), projected to $300B+ by 2032.
2. Rising hubs: Poland, Mexico, Vietnam, Philippines, Singapore—each complementing India’s dominance.
3. Two operating archetypes:
Global_Business_Centers (GBC/GBS³): run-the-business efficiency, SLA⁴-driven.
Global_Capability_Centers (GCCs): change-the-business innovation, IP⁵ creation.
The_Big_4_signals
1. Deloitte: India is the world’s 1 shared services destination; resilience means multi-region footprints.
2. PwC: GCCs now measured by profitability, productivity, and cash flow, not just cost.
3. EY: ~80% of enterprises already run on GBS frameworks; ER&D⁶ contributes >50% of GCC revenues.
4. KPMG: By 2026, GenAI⁷ will reshape service delivery—KPIs⁸ shift from savings to outcomes & innovation velocity.
KtalystLens:
The story is no longer about cost arbitrage. It’s about capability arbitrage.
AI manages data, Humans keep the lights on, & build the future.
Together, they form the dual spines of global enterprises deciding whether a company merely saves money or creates enduring value. The question isn’t where these centers are located anymore. It’s what they’re truly capable of.
Will the next MegaGCCs rise in Tier-2 Indian cities, ASEAN, or nearshore Americas, and more importantly, will they run on cost, creativity or Sustainability?
Footnotes:
1. GCC – Global Capability Center (sometimes called Global Capacity Center)
2. BFSI – Banking, Financial Services, and Insurance
3. GBS – Global Business Services (umbrella term for shared services / GBC)
4. SLA – Service Level Agreement
5. IP – Intellectual Property
6. ER&D – Engineering Research & Development
7. GenAI – Generative Artificial Intelligence
8. KPI – Key Performance Indicator
Originally published on LinkedIn on 2025-10-03 06:39:16: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A82951-7379766976807604224
KtalystNamasteIndia CostHavens to CapabilityEngines: The GCC Revolution
USD_128_billion & counting, that’s not the GDP of a small country it’s the market size of Global Capability Centers (GCCs¹).
NamasteIndia, with it’s 1,900+ centers and ~2 million professionals, is at the epicenter of this silent revolution.
NamasteIndia_Epicenter
1. ~1,900+ GCCs employ ~2 million people, contributing ~$60B today headed to ~$80B in 5 years.
2. Only 5% are “Mega GCCs” (>5,000 employees, $1B+ parent revenue), yet they house ~50% of India’s GCC talent.
3. Leading verticals: Telecom, Software, BFSI², Semiconductors, Healthcare.
4. 70+ more Mega GCCs are expected in India within the next 5 years.
GlobalTrends
1. Market size: $128B (2023), projected to $300B+ by 2032.
2. Rising hubs: Poland, Mexico, Vietnam, Philippines, Singapore—each complementing India’s dominance.
3. Two operating archetypes:
Global_Business_Centers (GBC/GBS³): run-the-business efficiency, SLA⁴-driven.
Global_Capability_Centers (GCCs): change-the-business innovation, IP⁵ creation.
The_Big_4_signals
1. Deloitte: India is the world’s 1 shared services destination; resilience means multi-region footprints.
2. PwC: GCCs now measured by profitability, productivity, and cash flow, not just cost.
3. EY: ~80% of enterprises already run on GBS frameworks; ER&D⁶ contributes >50% of GCC revenues.
4. KPMG: By 2026, GenAI⁷ will reshape service delivery—KPIs⁸ shift from savings to outcomes & innovation velocity.
KtalystLens:
The story is no longer about cost arbitrage. It’s about capability arbitrage.
AI manages data, Humans keep the lights on, & build the future.
Together, they form the dual spines of global enterprises deciding whether a company merely saves money or creates enduring value. The question isn’t where these centers are located anymore. It’s what they’re truly capable of.
Will the next MegaGCCs rise in Tier-2 Indian cities, ASEAN, or nearshore Americas, and more importantly, will they run on cost, creativity or Sustainability?
Footnotes:
1. GCC – Global Capability Center (sometimes called Global Capacity Center)
2. BFSI – Banking, Financial Services, and Insurance
3. GBS – Global Business Services (umbrella term for shared services / GBC)
4. SLA – Service Level Agreement
5. IP – Intellectual Property
6. ER&D – Engineering Research & Development
7. GenAI – Generative Artificial Intelligence
8. KPI – Key Performance Indicator
Originally published on LinkedIn on 2025-10-03 05:58:04: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7379756604793102336
GeoShock: When_Politics_Hijack_Profit_Planet & Production
War rooms are the new boardrooms—because supply chains don’t salute borders.
KtalystKeystone
The world isn’t flat anymore—it’s fractured.
And business isn’t just about strategy—it’s about survival through shifting borders.
McKinsey Economic Outlook (Mar 2025) confirms it:
Geopolitics is now Boardroom Agenda 1.
Margins, maps, and mandates are colliding.
TheTripleShock
Industry | Profit | Planet
Industry Impact – ReroutingResilience
68% of global manufacturing execs rank geopolitics as a top 3 business risk
🔄 EVs & Batteries: 30–40% price swings due to unstable lithium/cobalt supply
⛔ Pharma: Indian exports to CIS & Africa fell 9% in Q1 2025 (port + policy delays)
🔐 Tech Platforms: 25%+ new integrations delayed by cross-border data laws
Geopolitics is no longer background noise—it’s the beat driving every business decision.
ChristineLagarde
Profit Impact – MarginsAtWar
📉 2.4% YoY EBIT drop in firms exposed to volatile regions
🚧 #$170B in CapEx shelved globally in 2024 due to policy unpredictability
💸 #$130B+ lost to EM currency swings (J.P. Morgan)
🧾 Carbon Taxes: 8–14% cost surge for Indian metals under EU CBAM
If you’re not worried, you’re not paying attention.
RayDalio
Sustainability Impact – NetZeroInNeutral
🌍 Only 12% of firms are 2030-net-zero aligned (UNEP)
⚠️ Green Protectionism: 50+ disputes on clean-tech subsidies
🛢️ Fossils up 5%, Renewables down 22% in conflict zones
❌ 47% of investors doubt ESG claims’ credibility (Bloomberg, 2025)
Control oil and you control nations; control food and you control the people.
HenryKissinger
ExploreFurther
Michael Froman on business & geopolitics
Daniel Yergin on energy & world order
CEO Guide: Tariff Moves 2025
Global Trade Geometry – The New Map
KtalystView | ProfitVsPlanet | GeoShock | GlobalRiskMatrix | SustainableStrategy | GreenProtectionism | NetZeroInNeutral
Originally published on LinkedIn on 2025-04-20 18:37:00: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A2474261-7319791211194515457
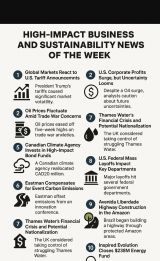
Decoding_an_Eventfull_Week: 10GlobalShifts That_Will_Shape_Your_Boardroom_YR2025
From tariffs to tarmac, profits to policies—here’s how decision-makers should read the signals before they shake the strategy.
10_Global_Moves | 10_Business_Ripples | 10_Smart_Perspectives
Curated by: KTALYST KEYSTONE
US_Tariffs on India – Trade Flashpoint
China absorbs with subsidies.
Vietnam escapes via FTAs.
India should attract FDI: “Tariffed there? Manufactured here.
Oil_Price_Volatility – Energy Chessboard
India secures discounts, but remains exposed.
U.S. shale pumps faster, EU scrambles.
Time to pivot to biofuels & hydrogen early.
US_Corporate_Profits – High but Hollow
204B profits, but 15% layoffs.
Big Tech trims fat, not revenue.
Efficient Excellence is the new productivity playbook.
BASF’s Green Push – Playing Catch-Up
Croda leads with 61% green revenue.
Evonik innovates, BASF delays.
Mindset shift needed: sustainability as profit driver.
Canadian_Climate_Fund_Shift – Municipal Muscle
CAD 20M goes green locally.
Outperforms federal climate spend.
Cities will lead, not capitals.
Eastman_Offsets_Emissions – Scope 3 Moves In
Unseen emissions, now seen.
Eastman acts, others talk.
Scope 3 = License to Operate soon.
Thames_Water_Crisis – Leaky Logic
#£15B in debt, bailout looming.
Japan, Singapore guard infra smartly.
Water isn’t just utility, it’s national security.
US_Federal_Layoffs – Silent Collapse
35,000 cut, while EU hires for AI & climate.
India upskills, U.S. downsizes.
Public policy needs people, not contractors.
AmazonHighway – Brazil’s COP Contradiction
Protected zones bulldozed.
Kenya, India build green infra, Brazil risks COP30 face.
Tarmac over trees = Trust deficit.
10. Inspired_Evolution_Fund – Africa Powers Up
#$238M clean energy fund.
1.7x bigger than Acumen 2023.
Africa can leap, if policies match capital.
Quote_of_the_Week:
Every ripple in global policy or boardroom signals a tide shift in power, purpose, and preparedness. Those who read early, move early.
KTALYSTKEYSTONE
Originally published on LinkedIn on 2025-04-03 12:18:18: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7313535315867054080
Greenwashing Exposed: Why 68% of “EcoClaims” Are Just Dirty Laundry in a GreenShirt
Is greenwashing fueling growth or fast-tracking brand destruction?
Turns out—it’s not just misleading, it’s backfiring hard.
Here’s how companies played the game—and got played instead:
Short-Term Shine, Long-Term Slap
🌿 Volkswagen lost over $35 billion in fines and lawsuits after its “clean diesel” scandal
🌿 ₹Nestlé faced global backlash for branding single-use plastics as “sustainable
🌿 H&M’s “Conscious Collection” was called out for lack of measurable impact
Result? Green trust turned toxic.
Lesson: You can’t plant lies and expect green shoots.
Investor Bait with ESG Plate
💰 In 2023, $4.9 trillion in assets were under ESG management—yet a Morningstar report delisted over 1,200 funds for greenwashing
💰 Big Oil promoted net-zero plans while emissions rose by 8% in some cases
💰 Fast fashion boasted carbon offsets, but only 2% of brands met reduction goals
Result? ESG funds got spooked, and regulators got busy
Lesson: You can’t polish your portfolio with pixelated promises
Backlash Bonanza
⚖️ Coca_Cola ranked as the 1 plastic polluter four years in a row—despite “100% recyclable” claims
⚖️ Unilever was flagged by watchdogs for inconsistent environmental messaging
⚖️ Over 60% of GenZ consumers say they’d boycott brands caught greenwashing
Result? Fines, lawsuits, and meme-fueled brand bashing
Lesson: Greenwashing is like cheating on a public exam. Cameras are everywhere.
From Fake to Awake
♻️ Microsoft got grilled over Scope 3 emissions—then released a transparent climate report
♻️ Adidas replaced slogans with substance: circular design, verified materials
♻️ Patagonia went bold, declaring Earth its “only shareholder
Result? Redemption stories that resonate
Lesson: Authenticity isn’t an add-on—it’s your only lifeline
FinalThoughts:
A 2024 study revealed that 68% of sustainability claims by brands were either exaggerated or unverifiable.
In today’s world, greenwashing isn’t just risky—it’s a reputationruiner and a legal landmine.
In 2025, the true green winners will be those who walk the talk—not just talk the tagline.


Originally published on LinkedIn on 2025-03-24 16:24:41: https://www.linkedin.com/feed/update/urn%3Ali%3Ashare%3A7309973442575974403
Greenwashing Exposed: 11_Companies That Got Caught!
🌍 Sustainability is a business imperative. Fake green claims aren’t just unethical—they’re costly.
⚽ 1 FIFA – The “Carbon-Neutral” World Cup Myth
📢 Claim: Qatar 2022 was 100% carbon-neutral.
📊 Reality: Actual emissions were 3X higher than FIFA reported. Carbon credits used were questionable.
💰 Backlash: Carbon Market Watch called it “climate deception.
🚗 2 Volkswagen – The $33B Diesel Lie
📢 Claim: “Clean diesel” cars with low emissions.
📊 Reality: Vehicles emitted 40X above legal NOx limits.
💰 Backlash: $33B in fines & lawsuits (Dieselgate).
☕ 3 Keurig – “Recyclable” Pods That Weren’t
📢 Claim: Pods are 100% recyclable.
📊 Reality: Most recycling centers rejected them.
💰 Backlash: $3M fine in Canada for misleading claims.
🍔 4 McDonald’s – A Green Logo, Not Green Actions
📢 Claim: New green-and-yellow logo reflected sustainability.
📊 Reality: No real operational changes to reduce waste or emissions.
💰 Backlash: Public dismissed it as cosmetic rebranding.
👗 5 H&M – The “Conscious” Collection That Wasn’t
📢 Claim: Ethical, sustainable fashion.
📊 Reality: Lack of transparency, over-reliance on fast fashion.
💰 Backlash: UK & Norway regulators investigated false claims.
🥤 6 Coca_Cola – The 70% Plastic “PlantBottle
📢 Claim: Eco-friendly bottle made from plant-based plastic.
📊 Reality: Only 30% plant-based, rest was petroleum plastic.
💰 Backlash: 1 global plastic polluter (Break Free from Plastic Report).
🛢 7 BP – “Beyond Petroleum” or Just PR?
📢 Claim: Heavy investments in renewables.
📊 Reality: Only 4% of BP’s budget went into green energy.
💰 Backlash: Media and activists called out the misdirection.
💄 8 L’Oréal – “Sustainable Beauty” with a Plastic Problem
📢 Claim: Ethical beauty products with lower carbon impact.
📊 Reality: Plastic-heavy packaging, unsustainable ingredients.
💰 Backlash: Exposed for greenwashing without meaningful changes.
✈ 9 Ryanair – The “Lowest Emissions” Airline Claim
📢 Claim: “Europe’s lowest emissions airline.
📊 Reality: UK regulators banned the ad for misleading data.
💰 Backlash: Campaign forced to be withdrawn.
👟 10 Adidas – “Ocean Plastic” Sneakers That Weren’t
📢 Claim: Shoes made of 100% recycled ocean plastic.
📊 Reality: Only a fraction was from ocean waste.
💰 Backlash: Sustainability claims faced scrutiny.
🚰 11 Nestlé – The “Sustainable” Water Extraction Scandal
📢 Claim: Bottled water is “sustainably sourced.
📊 Reality: Over-extracted from drought-prone areas.
💰 Backlash: Faced lawsuits, protests, and reputational damage.
🚨 Takeaways
✅ Fake green claims = regulatory & reputational risk.
✅ Consumers demand transparency & data-backed sustainability.
✅ Sustainability isn’t a PR stunt—it’s a long-term commitment.
Sustainability BusinessEthics GreenwashingFails BrandReputation


Originally published on LinkedIn on 2025-03-15 05:41:42: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A4385073-7306550139257577472
#️⃣ HarvestingtheSunTwice: TheAgrivoltaicsRevolution🌞🌾
🌍 Agrivoltaics—farmingandsolarpowercombined—isreshapinglanduseefficiency. This innovation boosts cropyields,waterconservation,andincreasescleanenergyoutput.
📈 MarketGrowth 🟢 #$4.59BMarket(2024),Projectedto$23.84Bby2034 – CAGR of 16.76%, driven by rising solar adoption. (marketresearchfuture.com) 🟢 14GWInstalledGlobally – Germany alone has a potential 1,700GW, showing massive scalability. (sens-energy.com)
🌾 AdvantagesofAgrivoltaics 🟢 70%IncreaseinLandEfficiency – Dual land use maximizes productivity. (vectorenewables.com) 🟢 200%HigherTomatoYield,300%forPeppers – Shaded crops thrive under controlled conditions. (mbtenergy.com) 🟢 47%LessWaterNeeded – Solar panels reduce evaporation, benefiting drought-prone regions. (mbtenergy.com)
🌍 GlobalAdoptionTrends 🌱 USA: 500+AgrivoltaicSites generating 9GW of solar power. (en.wikipedia.org) 🌱 Europe: Germany and France leading R&D and implementation. (en.wikipedia.org) 🌱 Asia: Japan and China scaling agrivoltaics in rural solar programs. (en.wikipedia.org)
⚠️ ChallengesAhead 🔴 HighInitialInvestment – Cost barriers slow adoption. (mdpi.com) 🔴 ComplexDesignIntegration – Requires precision in panel spacing and crop selection. (mdpi.com) 🔴 CropCompatibilityIssues – Not all plants benefit from shading. (mdpi.com)
🐑 InnovativeApplications 💡 SolarGrazing: 3,000Sheep maintain vegetation under solar farms in Texas. (apnews.com) 💡 PollinatorSolarFarms: Solar arrays double as bee-friendly habitats. (newyorker.com)
🚀 TheFutureIsBright – Agrivoltaics mergesfoodsecurityandcleanenergy, but scaling requires policy support, innovation, and global collaboration.
💡 Wouldyousupportagrivoltaicsinyourregion?Dropyourthoughtsbelow!👇
Originally published on LinkedIn on 2025-03-03 07:26:27: https://www.linkedin.com/feed/update/urn%3Ali%3AgroupPost%3A82951-7302227847153160192

